Crypto Analytics Tools: How to Research Tokens Without Dashboard Overload
 By Darlene Aberin Updated
Crypto investors do not suffer from a lack of data. The harder problem is deciding which data answers the question in front of them.
A token page can show market capitalization, but not necessarily whether a handful of wallets control supply. A blockchain explorer can show every transaction, but not what the activity means economically.
A DeFi dashboard can report total value locked, but TVL is not the same as revenue. A wallet-intelligence platform can label entities, but an entity label is still an interpretation layered on top of public blockchain records.
That is why the best crypto analytics tools are not the ones with the most charts. They are the ones used for the right question.
The practical approach is to build a research stack. Start with broad market context, then verify the asset and contract. After that, examine liquidity, supply, and protocol fundamentals, and use on-chain data to test claims a token profile cannot answer.
This guide compares the major categories of crypto analytics tools and explains what each category can and cannot tell you.
Key Takeaways
- Use tools by question, not popularity: Market-data platforms, explorers, protocol dashboards, SQL analytics, and wallet-intelligence tools solve different problems.
- Verify definitions before comparing numbers: TVL, fees, revenue, circulating supply, volume, and liquidity are not interchangeable.
- Start broad, then go on-chain: Market data is useful for screening; transaction-level evidence is better for verifying specific claims.
- Contract identity comes before analysis: A correct token name and ticker are not enough. Verify the contract address.
- Liquidity deserves its own check: Market capitalization can look impressive while executable liquidity remains thin.
- Protocol activity needs context: High transactions, users, or fees can reflect different economic behaviors depending on the protocol.
- No dashboard removes judgment: Every metric has methodology, coverage, and labeling limits.
The Research Stack Starts With the Question
“Which crypto research tool is best?” is usually the wrong question. A better question is: what are you trying to establish?
| Research Question | Best Tool Category |
|---|---|
| What is the token’s price, market cap, volume, and supply? | Market-data platform |
| Is this the correct contract? | Blockchain explorer |
| Who holds or moves the token? | Explorer or wallet-intelligence platform |
| How much value is deposited in the protocol? | DeFi fundamentals dashboard |
| What fees and revenue does the protocol generate? | Protocol economics platform |
| Are wallets accumulating, selling, or interacting? | On-chain analytics |
| Can I reproduce a custom metric? | SQL/blockchain query platform |
| How liquid is a trading pair? | DEX or market-liquidity analytics |
| What does a named entity hold? | Labeled wallet intelligence |
| How does the token compare with peers? | Market and sector analytics |
The point of a research stack is not to open every platform. It is to avoid asking one platform to answer a question its data was not designed to answer.
Market-Data Platforms Are the First Screen, Not the Final Verdict
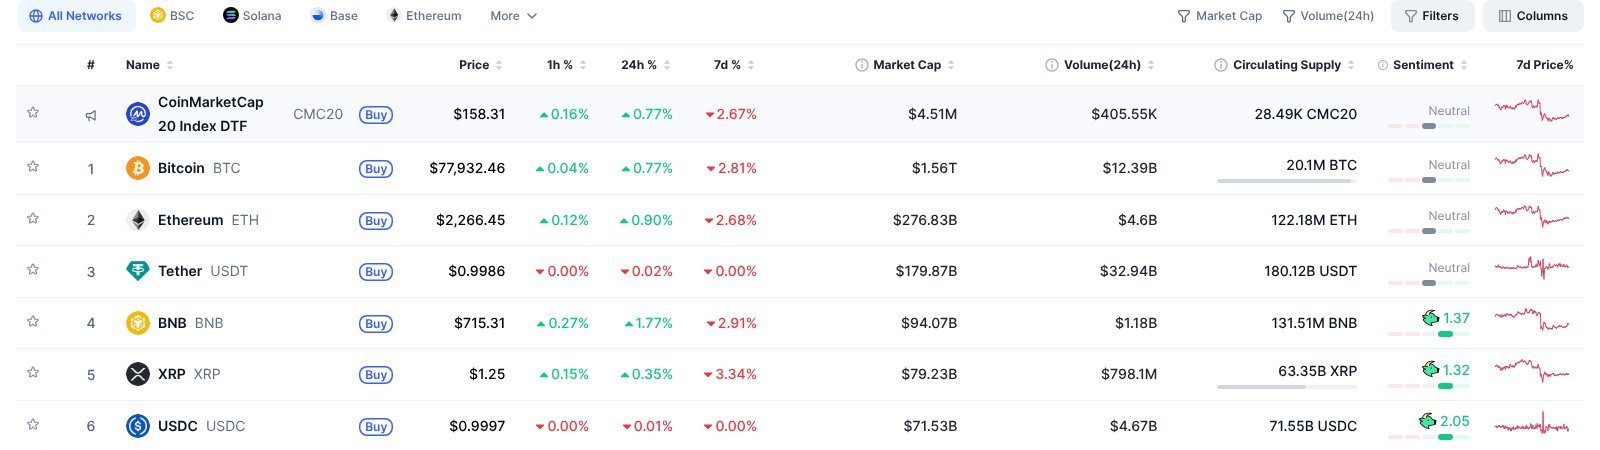
Broad crypto market platforms are useful because they standardize a large amount of basic information in one place. Typical fields include:
- Price
- Market capitalization
- Circulating supply
- Total supply
- 24-hour trading volume
- Historical prices
- Exchange listings
- Categories
- Contract addresses
- Market rankings

This is the first layer of crypto market research. It establishes what the asset is, how large its market appears to be, and how actively it trades before you move into deeper blockchain evidence.
The limitation is that each headline number has assumptions. Market capitalization, for example, is commonly calculated as price multiplied by circulating supply. If circulating supply is uncertain or inconsistently defined, the resulting market cap inherits that uncertainty.
Volume can also require interpretation. A large reported number does not by itself establish that liquidity is deep, evenly distributed, or executable near the quoted price. Use market-data platforms to frame the investigation, not end it.
Blockchain Explorers Are the Verification Layer
Explorers such as Etherscan expose blockchain activity more directly. They can help verify the following:
- The token contract
- Transfers
- Holder addresses
- Wallet balances
- Smart-contract interactions
- Contract source code when verified
- Transaction hashes
- Event logs
- Activity linked to specific addresses
Etherscan’s current documentation describes the service as a block explorer whose API serves the same on-chain data across more than 60 EVM-compatible chains. Its data can be especially useful when a dashboard makes a claim that can be traced back to public transactions.
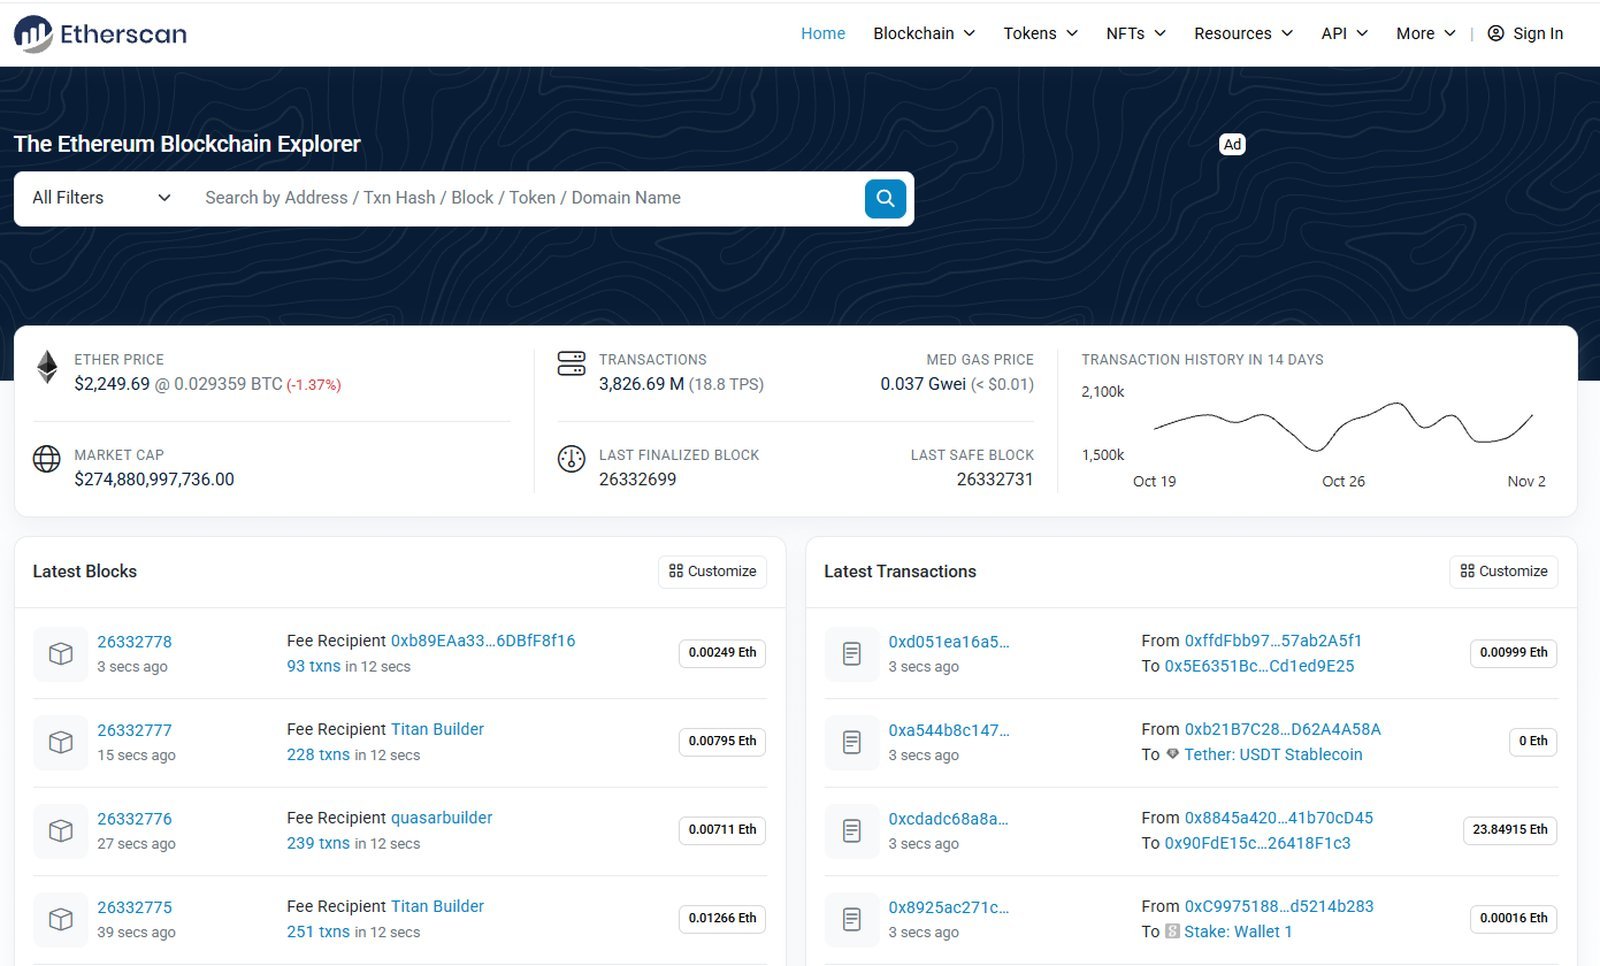
Suppose a project says a treasury transferred tokens to a market maker. A block explorer can help confirm whether the transaction occurred, when it occurred, which addresses were involved, and how much moved. What it cannot automatically tell you is why.
An address is not a business explanation. Transaction evidence must still be interpreted.
Contract Verification Should Happen Before Token Comparison
Crypto markets reuse names and symbols. Different tokens can share the same ticker, and scam tokens can copy branding. The same checks apply to anyone weighing a crypto airdrop before connecting a wallet.
That makes contract identity foundational. Before comparing a token across platforms:
- Find the contract address from the project’s official source;
- Verify it on an explorer;
- Confirm that the market-data platform references the same address;
- Check the network; and
- Verify that the trading pair being analyzed contains the correct asset.
Skipping this step can produce an impressively detailed analysis of the wrong token.
DeFi Dashboards Require Metric Discipline
DeFi analytics often introduce metrics that sound familiar but have specific definitions. DefiLlama’s data definitions define protocol TVL as the value of coins held in a protocol’s smart contracts.

It defines fees as the total fees users pay when using the protocol. Revenue is the portion of those fees the protocol keeps for itself, such as amounts going to a treasury, team, or token holders rather than liquidity providers.
Those distinctions count. If Protocol A generates $10 million in user fees but passes $9 million to liquidity providers, its protocol revenue is not $10 million under that definition. A table can make the distinction clear:
| Metric | What It Tries to Measure | Common Misread |
|---|---|---|
| TVL | Value deposited or held in protocol contracts | “Company value” |
| Fees | Amount users pay to use the protocol | Protocol profit |
| Revenue | Portion retained by protocol stakeholders | Total economic activity |
| DEX volume | Value traded through exchange contracts | Revenue |
| Borrowed amount | Outstanding borrowing activity | Deposits |
| Stablecoin supply | Tokens outstanding | Transaction volume |
A research article that says “Protocol X is larger than Protocol Y” without defining the metric may be comparing different ideas.
TVL Can Be Useful Without Being a Valuation Metric
TVL is widely used because it provides a simple view of capital committed to DeFi protocols. It is not the same as the market value of a company. TVL can rise because users deposit more tokens, token prices rise, incentives attract temporary capital, a protocol launches on new chains, or methodology expands coverage.
It can fall for the opposite reasons. If the assets inside a protocol appreciate sharply, dollar-denominated TVL can rise even if token quantities barely change.
Researchers therefore need to separate asset-price effects from new deposits when that distinction is important. TVL is best understood as an activity or capital-deployment metric whose meaning depends on protocol design.
SQL Analytics Platforms Let You Reproduce the Question
Prebuilt dashboards are convenient. Custom queries are more powerful when the exact question is unusual.
DuneSQL is designed for blockchain analysis and supports querying decoded blockchain data using SQL. Dune also makes decoded smart-contract calls and event logs available in structured tables for supported contracts.

That opens the door to questions such as how many unique wallets used a contract each month, what percentage of volume came from the top 20 traders, how many wallets returned after their first interaction, how much of a token moved through a particular contract, and how did behavior change before and after a governance proposal. The strength of SQL analytics is reproducibility.
The weakness is that a query can be technically valid and analytically misleading. Researchers must define:
- Which contracts are included
- What counts as a user
- Whether bots are excluded
- How addresses are deduplicated
- Which chains are covered
- How prices are applied
- How missing data is handled
A dashboard is only as good as its definition.
Event Logs Can Reveal More Than Transaction Counts
Smart contracts emit event logs when defined actions occur. Dune’s documentation notes that these logs are stored on-chain and can be decoded into structured tables.
For research, that means “transaction count” can often be replaced with a more precise event. Instead of counting every transaction sent to a protocol, you may count: swaps, deposits, withdrawals, liquidations, mints, burns, votes, or bridge transfers. This improves the connection between the metric and the behavior you are trying to study.
Wallet Intelligence Adds Entity Context
Raw blockchain data is pseudonymous. Wallet-intelligence platforms attempt to connect addresses with known or inferred entities.
Arkham’s documentation on entities, labels, and tags describes a system that groups or identifies on-chain addresses. Its platform can show holdings, transfers, counterparties, and wallet behavior associated with labeled entities. This can help answer questions such as:

- Are exchange reserves changing?
- Which wallets are linked to a fund or company?
- Did a large holder move tokens to an exchange?
- Are several addresses believed to belong to one entity?
The limitation is important: labeling introduces another layer of interpretation. A blockchain transaction is observable.
The statement “this address belongs to Entity X” depends on attribution quality. Serious research should distinguish the two.
Holder Concentration Needs Address Classification
A top-holder table can look alarming if exchange wallets and protocol contracts are not identified. Imagine the top address holds 20% of supply. That could be an exchange custody wallet representing many customers (crypto custody explains how those arrangements work), a vesting contract, a treasury, a bridge, a burn address, a liquidity pool, or an individual holder.
Those cases imply very different concentration risks. Instead of reporting “the top 10 wallets hold 60%,” classify the wallets when possible. A better table is:
| Holder Type | Share | Interpretation |
|---|---|---|
| Exchange custody | 18% | Represents customer balances, not one economic owner |
| Treasury | 14% | Governed by project or DAO |
| Vesting contracts | 12% | Subject to release schedule |
| Liquidity pools | 8% | Supports trading |
| Unidentified whales | 8% | Concentration risk requires more research |
The extra context turns a raw statistic into analysis.
Liquidity Tools Answer a Different Question From Market Cap
Market cap asks what circulating supply is worth at the quoted price. Liquidity asks whether trading can occur near that price. For a DEX pair, examine pool reserves, liquidity in dollar terms, 24-hour volume, price impact, slippage, number of active pools, concentration by venue, and whether liquidity is incentivized.
For centralized exchanges, look at order-book depth and spread when available. A token can have a large market capitalization and poor executable liquidity. That is important for both entering and exiting a position.
Supply Research Requires More Than One Field
A strong token-research workflow distinguishes:
- Circulating supply
- Total supply
- Maximum supply
- Emissions
- Burns
- Unlocks
- Treasury holdings
The gap between circulating supply and future supply can be economically significant. If only 10% of a token’s eventual supply is circulating, the present market structure may look very different after investor, team, or ecosystem allocations unlock.
Do not treat fully diluted valuation as a prediction. Use it as a way to frame how current price relates to a broader future supply base.
Social Data Is Context, Not Proof
Crypto research often includes X activity, Telegram membership, Discord activity, search interest, or developer discussion. These can help detect attention. However, they can also be manipulated.
Follower counts can be inflated, and engagement can be purchased. Bot networks can create the appearance of momentum.
Use social data to answer: is attention increasing, what narrative is driving discussion, and which announcements are attracting interest. Do not use it alone to establish: product-market fit, protocol usage, financial strength, or token value. Those require harder evidence.
Developer Activity Needs the Same Caution
GitHub activity can indicate active development, but raw commit counts are not a quality score. One repository may split changes into many commits.
Another may make fewer but larger changes. Some protocol work may happen in private repositories. Developer checks include:
- Release history
- Number of active contributors
- Cadence of meaningful updates
- Open issues
- Documentation quality
- Audits
- Whether the codebase used in production matches public repositories
Again, the metric should match the question.
Build a Four-Layer Crypto Research Workflow
A repeatable workflow prevents research from becoming random tab opening. The four layers below move from broad context to specific evidence.
Layer 1: Market Context
Begin with a broad market-data platform to see:
- Price
- Market cap
- Volume
- Supply
- Sector
- Listed venues
- Comparable assets
At this stage you are not looking for an edge. You are building a map.
Context prevents basic errors later. For instance, a token that looks cheap in isolation may simply sit in a sector where every comparable asset has fallen by a similar amount.
Layer 2: Contract and Liquidity Verification
Next, use a block explorer and venue-level liquidity data to confirm you are looking at the right asset. Check the contract address, the largest holders, the active trading pools, and recent transfers.
The goal of this layer is identity and tradability. A token can have an impressive market cap and still be impossible to sell in size, so depth counts for more than the headline figure.
Layer 3: Protocol Fundamentals
For DeFi and application tokens, move on to the activity the protocol produces: TVL, fees, revenue, users, transaction types, developer activity, governance, and treasury. For the governance side, DAO governance explains how token holders and delegates make protocol decisions. These figures show whether anyone is paying to use the product.
Read each metric with its definition beside it. Fees and revenue are different numbers, and crypto analytics tools do not always define them the same way.
Layer 4: On-Chain Behavior
Finally, use SQL analytics or wallet intelligence to test specific claims. The goal of this layer is evidence, and it works best when you start with a question you can prove wrong.
Suppose a token narrative says “whales are accumulating.” This is where you check whether large or labeled wallets are increasing their balances, or whether the claim rests on a single transfer between exchange wallets.
A Tool Comparison Framework
Instead of ranking crypto analytics tools from best to worst, evaluate each type by the work it is suited to perform.
| Tool Type | Strength | Main Limitation |
|---|---|---|
| CoinMarketCap/CoinGecko-style market data | Broad market screening | Aggregated data needs deeper verification |
| Etherscan-style explorer | Transaction and contract verification | Requires interpretation |
| DefiLlama-style fundamentals | Protocol and chain comparisons | Metric definitions vary by protocol |
| Dune-style SQL analytics | Custom reproducible blockchain analysis | Requires query design |
| Arkham-style wallet intelligence | Entity and wallet context | Labels may involve attribution assumptions |
| DEX analytics | Liquidity and trading behavior | Often venue- or chain-specific |
| Developer repositories | Code and release activity | Activity volume is not code quality |
The best stack depends on the asset. A Bitcoin researcher needs different tools from a researcher analyzing a new lending protocol.
Common Research Mistakes
Six mistakes account for most misread dashboards in crypto analytics tools. Each one comes from reading a number without checking what it measures.
Comparing Metrics With Different Definitions
Two dashboards can both display “revenue” while counting different things. One may include fees paid to liquidity providers, while another counts only what the protocol keeps.
Before you compare figures across platforms, read each methodology page. If the definitions differ, the comparison tells you about the dashboards and not about the protocols.
Treating Missing Data as Zero
A blank field often means the platform does not cover that chain or protocol. It does not mean that no activity exists there.
This counts most for newer networks, where coverage arrives late. Check whether the tool supports the chain at all before you conclude that a protocol has no users or no volume.
Using One Day of Volume as a Long-Term Signal
A single day can be distorted by a launch, an incentive program, an exchange listing, or a market-wide move. Volume on that day says little about normal demand.
Look at several weeks at least, and note what happened on the unusual days. A spike that fades as soon as rewards end is evidence of the incentive, not of the product.
Ignoring Stablecoin and Native-Asset Denominations
A dollar figure can rise because the underlying token price went up, even when nothing else changed. TVL is especially exposed to this effect, since it is the value of deposited assets.
Where the tool allows it, view the metric in the native asset as well as in dollars. If deposits are flat in tokens but higher in dollars, the price moved and the activity did not.
Assuming Labeled Wallets Are Infallible
Wallet labels are inferences made by an analytics provider, and they can be revised or simply wrong. An address tagged as a fund or an exchange is a well-informed guess unless the owner has confirmed it.
Keep two things separate in your notes: what the address did, which is observed, and who controls it, which is inferred. That habit stops a labeling error from becoming a false conclusion.
Confusing Users With Addresses
An address is not a person. One individual can control hundreds of wallets, while a single exchange wallet can hold the balances of thousands of customers.
As a result, “active addresses” can overstate or understate real usage. Treat the figure as a rough activity signal, and look for supporting evidence such as fees paid before you call it adoption.
How to Document Your Research
A simple research sheet should include:
- Question
- Metric
- Definition
- Source
- Time period
- Network
- Contract address
- Calculation
- Caveats
- Conclusion
This may feel slower than browsing dashboards, but it prevents a common failure: forgetting why a number was chosen.
Frequently Asked Questions
What Are Crypto Analytics Tools?
Crypto analytics tools organize market and blockchain data so you can research prices, supply, liquidity, protocol activity, wallets, and transactions without reading raw chain data yourself.
Which Crypto Research Tool Should I Start With?
Start with a broad market-data source for context. Then move to a blockchain explorer, and add specialist analytics only when your question needs protocol, wallet, or supply detail.
Is On-Chain Data Always Accurate?
The blockchain records themselves are deterministic, but the interpretation can be wrong. Address ownership, user counts, labels, and economic classifications all rest on assumptions made by the tool.
Is TVL the Same as Revenue?
No. TVL measures the assets held in a protocol's contracts under a stated methodology. Revenue measures the value the protocol keeps, which is usually a far smaller figure.
Can Market Cap Show Whether a Token Is Liquid?
No. Market cap is price multiplied by circulating supply. Liquidity depends on trading depth, venue conditions, and how much you can trade without moving the price sharply.
Do I Need Paid Tools?
Not necessarily. Free market data, explorers, protocol dashboards, and public blockchain data answer many research questions. Paid tools mainly add convenience, wider coverage, better labeling, and smoother workflow.
Resources
The following sources provide the primary or specialist evidence used to verify the claims and frameworks above.